- Contact Us Now: (800) 337-7755 Tap Here to Call Us
Hit by an Uninsured Driver in Florida? Here Is How a UM Claim May Help


Florida UM claims may allow you, members of your household, and passengers in your vehicle to seek compensation through your own auto policy when an uninsured, underinsured, or hit-and-run driver causes your injuries. UM coverage can help with medical bills beyond PIP, lost income, and, in qualifying cases, pain and suffering. Call 800-337-7755 for a free case review.
Florida is a no-fault state. Most drivers are required to carry personal injury protection (PIP) and property damage liability, but most are not required to carry bodily injury liability coverage. That means the driver who hit you may have little or no insurance to pay for a serious injury. Uninsured/underinsured motorist coverage, often called UM, is designed to fill that gap. Because you are making a claim against your own insurance company, many people expect the process to be simple. It often is not.
What UM Coverage Is and Why It Matters in Florida
UM coverage is optional coverage you buy to protect yourself, not the other driver. Under Florida Statute 627.727, insurers are generally required to offer UM coverage with auto liability policies, and a policyholder who does not want it typically must reject it in writing. If you never signed a valid rejection, you may have more coverage than you think.
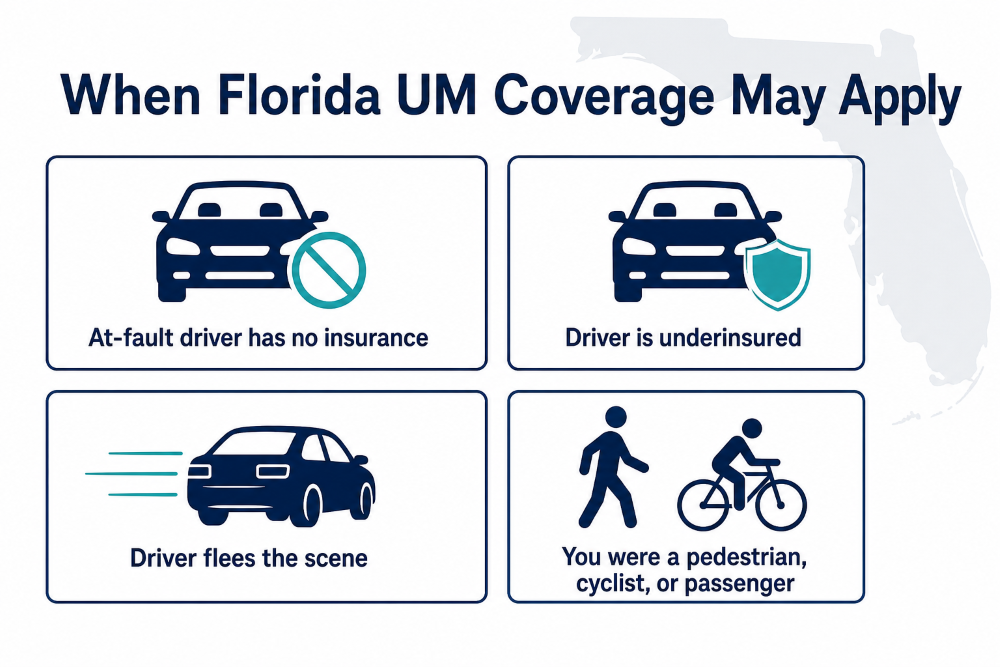
UM coverage may apply when:
- The at-fault driver has no insurance. This is the classic uninsured motorist situation.
- The driver is underinsured. Their bodily injury limits are too low to cover your losses.
- The driver flees the scene. Hit-and-run crashes may qualify for UM benefits.
- You were not in your own car. Depending on the policy, UM coverage may follow you as a pedestrian, cyclist, or passenger in someone else’s vehicle.
Stacked vs. Non-Stacked UM Coverage
Florida policies may offer stacked or non-stacked UM coverage. Stacked coverage can allow you to combine UM limits for each vehicle on your policy. For example, a household with three insured cars and stacked coverage may have access to more total UM benefits than a household with non-stacked coverage. Non-stacked policies usually cost less but may limit how much is available. Reviewing the declarations page and any signed selection forms is often one of the first steps in evaluating a claim.
Examples of Situations That May Lead to a UM Claim
The scenarios below are general illustrations of how UM coverage may come into play. They are not actual case results, and every claim depends on its own facts and policy language.
- A rear-end collision on I-75. A Broward County commuter is rear-ended by a driver who carries only PIP and property damage coverage. After PIP benefits run out, the injured driver’s own UM coverage may be the main source for remaining medical costs and lost wages.
- A cyclist struck in a crosswalk. A rider is hit by a car whose driver has a low bodily injury limit. The cyclist’s household auto policy may provide UM benefits even though the cyclist was not driving at the time. If you ride, our article on a cycling pedal cleat injury in Florida covers other ways riders may be hurt.
- A hit-and-run in a parking lot. A pedestrian is knocked down by a driver who leaves before anyone gets a plate number. A prompt police report and witness information may help support a UM claim.
- A rideshare passenger. A passenger is injured when another driver runs a red light. The claim may involve several policies, including the at-fault driver’s coverage, the rideshare company’s coverage, and the passenger’s own UM benefits.
- A fatal crash. When a crash with an uninsured driver takes a life, surviving family members may have rights under a UM policy. Our Florida wrongful death FAQs explain who may bring a claim.
How a Florida UM Claim Usually Works
- Report the crash promptly. Call police, get medical care, and notify your insurer as your policy requires.
- Use PIP benefits first. PIP generally pays a portion of medical bills and lost wages up to its limit, regardless of fault.
- Identify the other driver’s coverage. If they are underinsured, you may need to resolve their liability claim, often with your UM carrier’s consent, before pursuing UM benefits.
- Document your damages. Medical records, bills, wage loss proof, and evidence of how the injury affects daily life can all matter.
- Negotiate or litigate. If the insurer disputes fault, the extent of injuries, or the value of the claim, a lawsuit may become necessary. Our guide to the stages of a personal injury lawsuit in Florida walks through what that can look like.
Keep in mind that your own insurer may treat you like an opposing party once a UM claim is filed. Adjusters may request recorded statements, question whether your injuries were caused by the crash, or argue that your injury does not meet Florida’s permanent injury threshold for pain and suffering damages. Florida law also includes bad faith protections, and an insurer that does not handle a claim fairly may face additional exposure in some cases.
Common Mistakes That Can Hurt a UM Claim
- Settling with the at-fault driver too early. Releasing the other driver without notifying your UM carrier may affect your UM rights.
- Delaying medical treatment. Gaps in care are often used to argue an injury is minor or unrelated.
- Giving a recorded statement unprepared. Casual comments can be taken out of context.
- Assuming you have no coverage. A missing or defective rejection form may mean UM coverage still applies.
- Missing deadlines. Notice requirements and filing deadlines can apply, and they may differ from a standard negligence claim.
Why Choose the Law Offices of Jason Turchin
Attorney Jason Turchin founded the Law Offices of Jason Turchin, a personal injury firm based in Florida, and has spent his career helping people injured in car, motorcycle, bicycle, and pedestrian crashes deal with insurance companies, including their own.
Attorney Jason Turchin has an Avvo 10.0 Superb Rating and was AV Preeminent Peer Rated for Highest Level of Professional Excellence by Martindale-Hubbell in 2026. He has been on the Super Lawyers list from 2020 through 2026, and the firm has held an A+ BBB rating annually from 2014 through 2026. He is also a #1 Best Selling Author on Amazon.com on Accident Law.
The firm handles personal injury cases in Florida, New York, New Jersey and Washington, D.C., and throughout the U.S. with a network of co-counsels and local counsels. Cases are handled on a contingency fee basis, with fees and costs waived if there is no recovery. You can learn more about our Florida personal injury lawyers and about Attorney Jason Turchin.
Frequently Asked Questions About Florida UM Claims
Does Florida require drivers to carry UM coverage?
No. Florida generally requires insurers to offer UM coverage, but drivers may reject it in writing. Whether a valid rejection exists can be an important question in a claim.
Will filing a UM claim raise my insurance rates?
Florida law places limits on when an insurer can raise rates or cancel a policy based on a claim where you were not at fault. The specifics can depend on your situation and policy.
Can I make a UM claim if I was walking or riding a bike?
Possibly. Many policies extend UM coverage to the named insured and resident relatives even when they are not in a vehicle. Policy language controls.
What if the at-fault driver has some insurance?
If their bodily injury coverage is not enough to cover your losses, you may be able to pursue an underinsured motorist claim through your own policy after addressing their coverage.
Can I recover pain and suffering through UM?
You may, but Florida generally requires a qualifying injury, such as a permanent injury, before pain and suffering damages can be recovered in a car crash case. More general answers are available in our personal injury FAQs.
How long do I have to file a UM claim in Florida?
Deadlines can vary, and your policy may also have notice requirements. Speaking with a lawyer early can help you avoid missing a deadline.
Talk With a Florida UM Claims Lawyer Today
If an uninsured, underinsured, or hit-and-run driver injured you or a loved one, your own policy may offer a path forward. The Law Offices of Jason Turchin can review your coverage, explain your options, and help you deal with the insurer. Call 800-337-7755 or contact us online for a free consultation.
